Share industry information, process knowledge, release enterprise updates and detailed content on soldering techniques
In 2025, the solder paste industry has entered a stage of refined development, with customers significantly raising their requirements for product consistency, stability, and traceability. As electronic manufacturing processes continue to upgrade and industry competition intensifies, enterprises need to strengthen technological R&D and quality management to meet market demand for high precision and high reliability.
Tight global tin ore supply is driving the development of the solder recycling and reuse industry, and the proportion of secondary tin in solder raw materials is steadily increasing.
The expansion of 5G base station construction scale has driven the application demand for lead-free solders, bringing new growth to high-reliability welding materials.
The China-US trade friction has intensified price fluctuations in solder raw materials, and the volatile prices of key metals such as tin and silver have affected cost control for solder manufacturers.
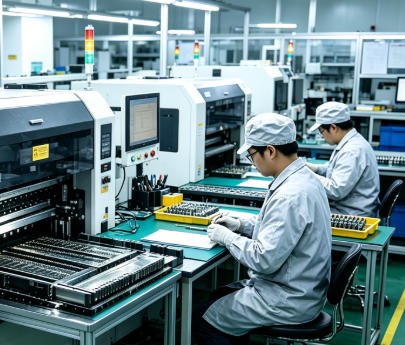
The SMT solder industry is accelerating its intelligent transformation, with Industry 4.0 technologies improving solder production consistency and quality control levels.
The COVID-19 pandemic has impacted the SMT solder supply chain, and solder manufacturers are addressing the challenges through inventory strategies and localized production.
The explosive growth of AI servers and AI terminal devices is driving the development of solder towards refinement and high reliability.
The application penetration rate of halogen-free solder paste in electronic manufacturing continues to increase, making it the preferred soldering material for high-reliability electronic products.
The Chinese SMT solder market is undergoing structural adjustment, with accelerated domestic substitution and products moving toward high-end development.
The successive revisions of the EU RoHS Directive continue to impact the global solder industry, driving solder products toward more environmentally friendly development.
Looking back on the lead-free transition in the SMT solder industry, the EU RoHS Directive has driven the global solder industry toward environmentally friendly transformation.
The global solder industry is accelerating its transition toward environmental friendliness and high-end products, with lead-free and halogen-free solder becoming the mainstream.
Optimizing the solder paste printing process is a key step in improving the efficiency of SMT production lines, and the collaborative optimization of printing parameters and stencil design enhances soldering yield.
Domestic solder brands are accelerating their progress in performance and service, gradually replacing the market share of imported solder paste in the mid-to-high-end market.
Sharp fluctuations in international tin prices are intensifying cost-control pressure on SMT solder enterprises, with hedging and formulation optimization becoming the coping measures.
The explosive growth of the new energy vehicle market has driven increased demand for power device solders, with IGBT and SiC module soldering emerging as a new growth driver.
Competition in the SMT solder industry continues to intensify. In early 2026, leading enterprises further squeezed market space through capacity expansion, technology integration and customer binding. Under multiple pressures such as fluctuating raw materials, rising environmental compliance costs and extended certification cycles for high-end products, small and medium-sized manufacturers generally face practical difficulties including lagging production line upgrades and order concentration toward leading players. The SMT solder sector is accelerating its shift from scale competition to a comprehensive contest of process adaptability and supply chain responsiveness.
In 2026, policy and regulation in the solder paste industry will become increasingly stringent, as environmental laws and regulations push enterprises to accelerate the R&D and promotion of halogen-free and low-VOCs products. As environmental requirements for electronics manufacturing continue to rise globally, solder paste enterprises face greater pressure in optimizing product formulations and upgrading production processes, while new opportunities for technological innovation and sustainable development are also brought to the industry.
The SMT solder technical standards have achieved substantial collaborative progress in early 2026. IEC/TC91 and SJ/T 11827-2023 have completed alignment on key parameters, covering melting point range, residue ion content, and wettability testing methods. This has increased the mutual recognition rate of materials among the electronic manufacturing clusters in the Yangtze River Delta, Pearl River Delta, and Chengdu-Chongqing region to 76%, significantly reducing the process debugging cycle and incoming material inspection costs for cross-region contract manufacturers.
Solder technology iteration in SMT has accelerated significantly. Starting from January 2026, Senju Metal Industry, Shengmao Technology, Indium Corporation, and Loctite China have successively launched new SMT solder products featuring low void rate, high wettability, and halogen-free enhancement, covering packaging scenarios from 01005 to fine-pitch BGA. Some products have passed production line verification by leading EMS manufacturers and entered the small-batch introduction stage.